Identification records your reviewers fill in, kept on every file
Collect ID documents online, have your reviewers record how each person was identified, note beneficial owners and sanctions screening, and keep it all with the application for as long as you need.
Where identification records fall apart
Anti-money-laundering identification rules ask you to record how you identified a person, not just to keep a copy of their ID.
A photocopy of the ID in a folder, and nothing about how it was checked.
Reviewers fill in an identification record: method, document, number, jurisdiction, expiry and date verified.
Beneficial owners of a corporation noted in an email.
A beneficial ownership record lists directors and owners of 25% or more, the structure and how it was confirmed.
Politically exposed person and third-party questions forgotten.
Both determinations are fields in the record, required before the reviewer can approve.
Records scattered when an examiner asks for them.
Each record is stored on the application, with the documents, the history and an access log.
Borrowers, guarantors, owners and new clients
Our team can add an identification record to any review step. This is the identity verification offering from our private lending template, used for guarantors, co-borrowers, directors and owners.
Identification record
Method, document, number, jurisdiction, expiry, second source and date verified.
Beneficial ownership record
Directors, owners of 25% or more, structure and how it was confirmed.
PEP and third-party questions
Asked of the person and determined by your reviewer.
Sanctions screening
Recorded by the reviewer, or run through your own provider.
Automated ID checks
Optional, through your own ID verification provider.
Retention up to 7 years
Kept with the application, then deleted automatically.
Access log
Every time staff open an application or download a file.
Export and erasure
Per application, with an erasure record kept.
Identity verification
Your privacy notice and consent to verify identification.
Including the politically exposed person and third-party questions.
Photo ID, plus an optional dated second document from a different source.
The reviewer fills in the identification record and the sanctions screening source and date.
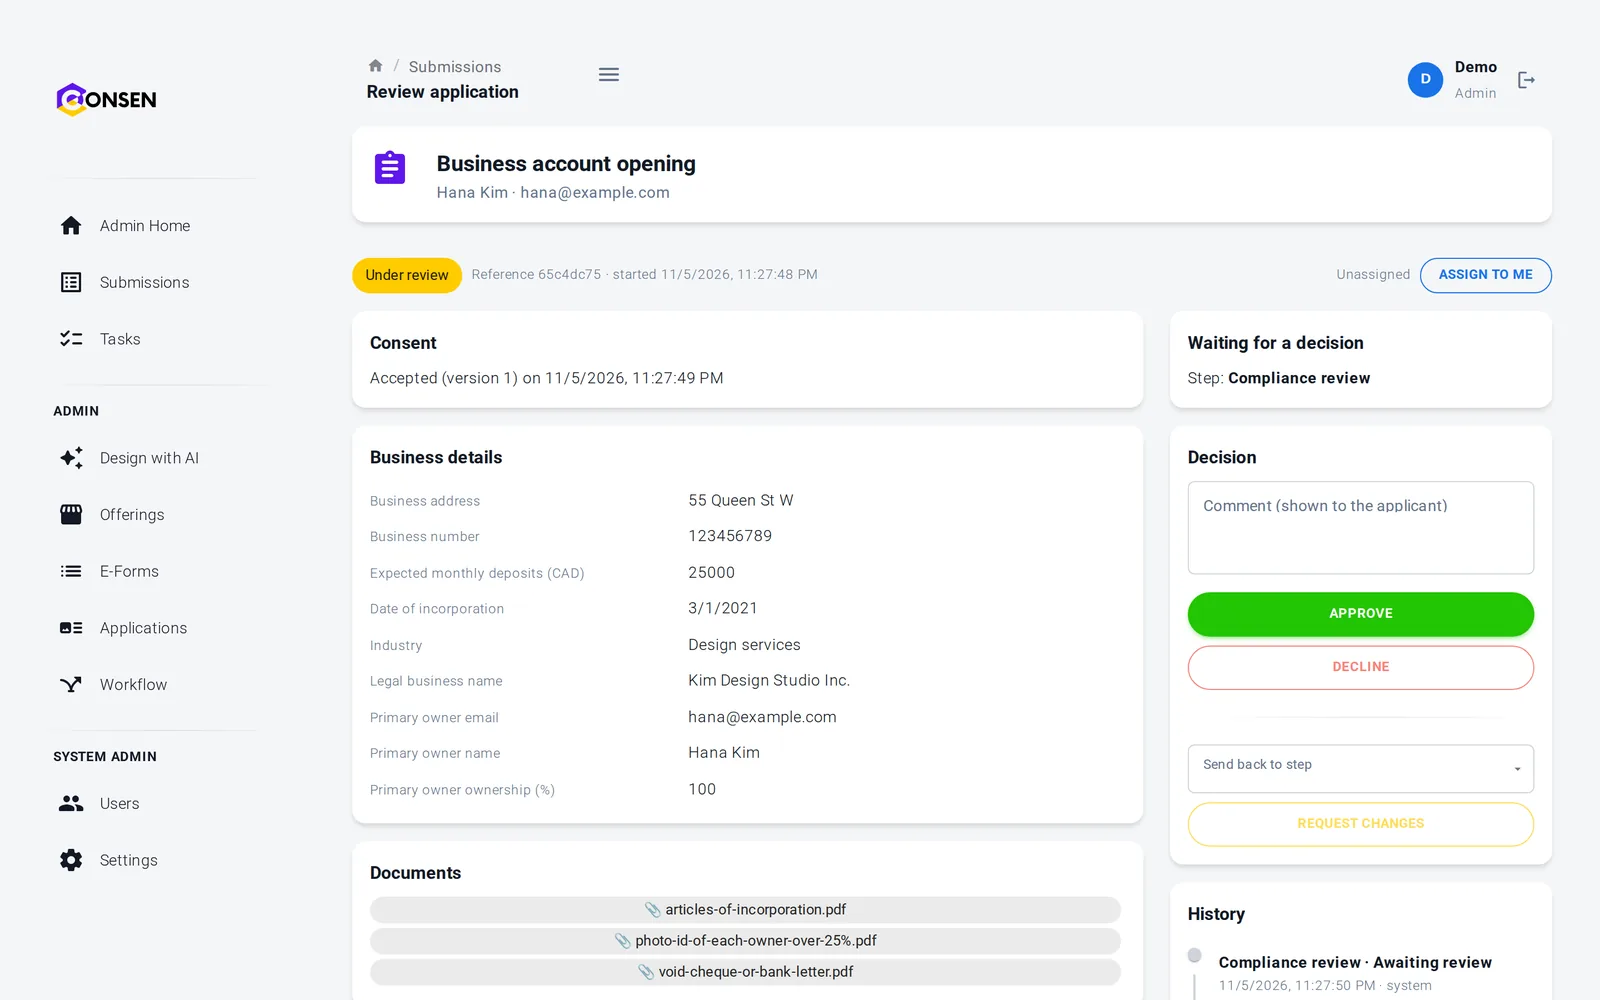
The record sits next to the documents
Reviewers see the person's answers and ID documents while they fill in the record. Required fields are needed only to approve, earlier rounds are kept, and a document request asks for anything missing.
Records visible to staff only
Required fields checked before approval
Earlier versions of a record kept
People upload their ID from their phone
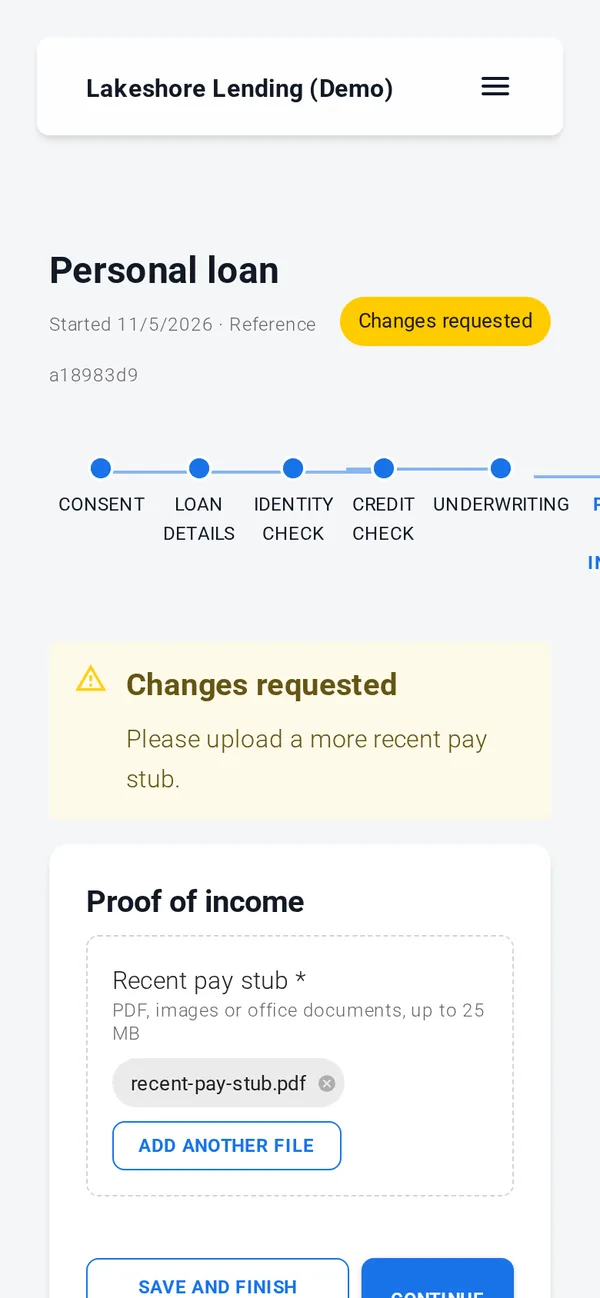
Each person gets their own link, consent and upload steps. They never see the record your reviewers fill in or the other people in the case.
Photos of ID straight from the phone
Save and finish later
Their own consent, recorded with time and version
Consent, documents, simple e-signature, rules, reviews and emails work out of the box. ID verification, credit, background and AML checks, advanced e-signature and payments run through your own provider accounts, connected with our team during onboarding; until then those steps run in test mode with simulated results.
Your compliance program decides; CONSEN keeps the record
The record fields are a structure for your reviewers, not a guarantee that a method meets the rules that apply to you. Your compliance officer decides which methods you use. Built on SOC 2 controls (independent audit planned); GDPR tools built in, DPA on request.
Two-step verification can be required for staff
Every staff access to an application is logged
Designers never see applications or documents
Erasure removes records with the application
Questions about identification records
No software can do that on its own. Your compliance officer decides which identification methods you use. CONSEN gives your reviewers a structured record to fill in for each person and keeps it on the file, with the documents, the history and an access log.
The method used, the document or source and its number, the jurisdiction, the expiry date, a second source when you use two, the date verified, whether the person is a politically exposed person or head of an international organization, whether a third party is involved, and the purpose of the relationship. Our team can add your own fields to the record.
Either through your own screening provider, connected as a step in the workflow, or by your reviewers, who record that they screened the person against sanctions and listed-person lists, the source they used and the date. Until a provider is connected, its step runs in test mode.
Staff only: applicants never see them, and designers can't open applications. Every staff access to an application is logged. You choose how long finished applications are kept, up to 7 years, and erasure removes the record with the application.
Yes. Invite each guarantor, co-borrower, director or owner to an identity verification offering with the same case reference. Each person has their own consent, documents and record, and your staff see them together.
The questions we hear first
Is our applicants' data safe?
Each workspace is isolated, data is encrypted in transit and at rest, staff access is role-based and invite-only, and every action is in the history.
How we protect dataHow much work is it to set up?
We set up your workspace and build the first application with you during onboarding. After that your team changes forms and rules itself, without code.
See the productDoes it work with our providers and systems?
Built-in steps need no third party. ID, credit and AML checks and payments connect to your own provider accounts. Sending data to your own systems is scoped with you.
Integrations and APIWhat does it cost?
There are three plans. We send a quote after a short call about your process and volume, so you pay for what you need.
Compare plansSee identification records on CONSEN
Tell us who you identify and how your compliance officer wants it recorded. We will show the record in a demo workspace.